
Capital requires several variations, therefore possible homeowners need dial-within the capital to suit form of demands. Antique mortgage brokers, like, fund antique possessions commands, usually stretching fees terminology to possess a-flat number of years. Payback times vary, nevertheless popular, conventional mortgage loans was paid more than a 30-year months.
Home owners which have guarantee inside their homes are often eligible for other sort of resource, hence spends supplies situated-up away from early in the day repayments to make sure loans. Home equity americash loans Yellow Bluff funds and you may personal lines of credit present flexible accessibility money, so they really was characteristically accustomed fund instructions exterior a primary a residential property purchase. Home improvements or other supplementary costs, particularly, are generally funded with one of these version of money.
Other distinct brand of financial support addresses costs associated with strengthening the fresh structures. Such home structure financing bear similarities for other different actual estate financing, however, you will find book requirements to possess domestic developers and you may possible domestic owners to look at whenever trying to investment getting strengthening tactics.
Collateral Takes on a crucial role
Prior to most other loans carried by the people, mortgages was big. Thousands of bucks are generally needed to personal household orders, very loan providers bring-to the immense exposure extending a mortgage. In order to eliminate the exposure publicity, finance companies, borrowing from the bank unions and you will finance companies have confidence in appraisals and rehearse the new built-in worth of property while the collateral to make sure mortgage loans. In fact, loan providers theoretically hold control up until that loan is completely met, from which big date a deed of possession is approved in order to an enthusiastic individual. Whenever buyers can not carry on with that have repayment, simultaneously, home loan owners feel the directly to foreclose and you can recoup losings from the offering the newest properties.
No matter if financial institutions prefer to only assemble money and you will profit from focus put in for each mortgage, this new security given by existing property brings a back-up facing financial losses, is to a borrower default. Similarly, household equity money uses your home resource just like the equity, decorating an opportunity out of recourse when cost words aren’t found. A significant variation distinguishes design financing from other kinds of assets resource, because the cash is provided without pre-established property security.
Builders and you can Customers Look for The Property Financing
To create-of conventional home commands, potential people deal privately that have banking institutions and other lenders in order to secure financial support. This new construction, as well, adds a creator on equation, that can replace the way money is actually administered. Before the recent market meltdown, such as for instance, developers had widespread entry to resource for new structure projects. As a result, framework enterprises aren’t financed creation, the help of its very own info to cover cost of materials and you may work.
Although well-situated builders nevertheless draw their funds to possess structure projects, less construction companies don’t usually gain benefit from the exact same investment benefits made use of prior to the home loan field downturn. Used, it indicates today’s potential homeowners will safer construction finance compared to the builders accountable for raising the formations.
Hard to Meet the requirements?

Such financing will likely be more difficult so you can qualify for and hold a good notably higher level of interest because there are significantly more details, unknows & threats toward bank. Also a well-known creator can be seen due to the fact a life threatening risk in a number of elements, and you may proprietor established adds various other level out-of chance.
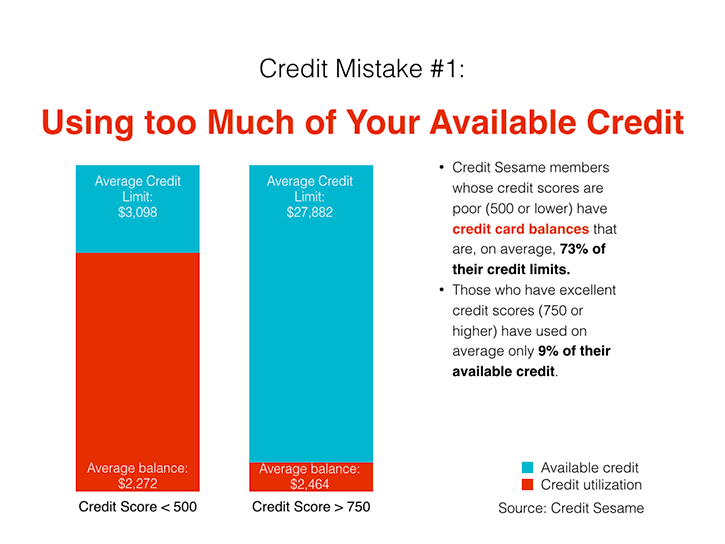
Due to the insufficient existing security and you may greater risk exposure getting lenders, it could be hard to qualify for a house design financing. And since new financing is often times provided to people, in lieu of developers, your own solid credit rating is the most important basis influencing eligibility. A beneficial credit score and you will substantial advance payment are requisites having build fund, prior to a person’s loan is approved, the new creator is additionally susceptible to history and you may borrowing checksparing certain forms of money depicts secret differences when considering build money or other sort of possessions fund.