
Next mortgage loans and you will family collateral fund are one out of a similar. Commercially property collateral loan was a second financial, as guarantee mortgage or HELOC sits into the 2nd standing for the title for the house. One another domestic equity funds and second mortgages are ways to obtain from the value of your residence therefore their foolish to listen in order to loan officers compare both some other financing circumstances.
These two financial support choices use your property while the collateral, however, around can be found differences between them brand of second financial programs, the brand new HELOC and you may house security loan. A property guarantee mortgage enjoys a fixed simple interest and are paid owing to consistent monthly installments, while an additional mortgage can get changeover regarding a predetermined so you’re able to a beneficial adjustable rate of interest.
Examine Household Security Fund vs. HELOC
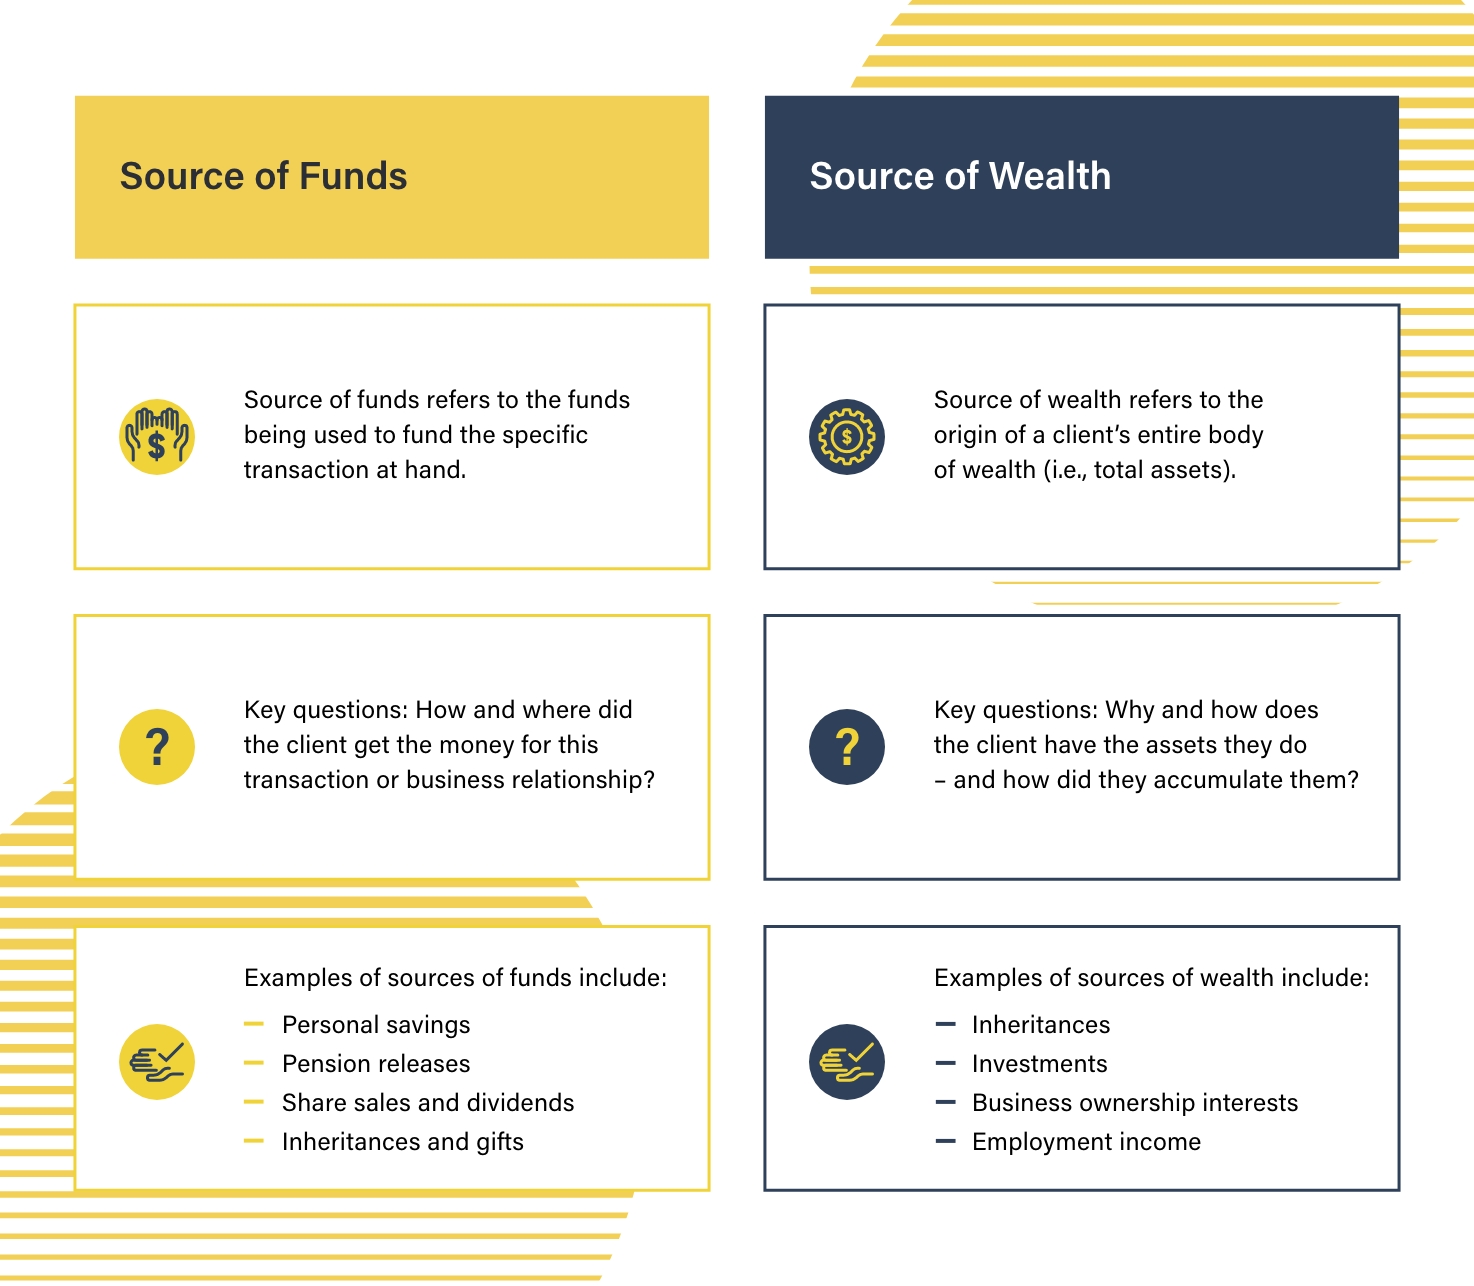
Property equity personal line of credit (HELOC) contains the liberty in order to withdraw money from a personal line of credit, if you find yourself one minute financial disburses a lump sum payment.
Each other choices show preferred advantages and disadvantages, such as the chance of foreclosures in the eventuality of non-repayment, the chance of bad collateral, including second loan charges and you will related charges.
What’s the next Mortgage?
A moment home loan is another financing removed up against your house that already enjoys home financing. Property owners have a tendency to remove 2nd mortgages to cover renovations, such domestic renovations, paying personal debt, or financial support expenses. 2nd-mortgage brokers give security money and lines of credit.
- A house collateral financing are a fixed-price, lump-sum mortgage with a term ranging from four to help you 3 decades. The new homeowner pays straight back the borrowed funds when you look at the fixed costs per month up until the loan was paid off.
- A home guarantee mortgage was ideal for your to cover a one-go out big expense, for example buying one minute house or paying playing cards.
- Consumers may all the way down the month-to-month costs in debt-combination out of a home guarantee financing.
- Domestic guarantee finance possess repaired pricing as well as the repayments is actually locked set for living of the mortgage, that makes your cost management convenient.
- Your home obtains the home equity mortgage, and that means you risk dropping the house or property if you do not pay.
- A property security line of credit is yet Albuquerque company outsource personal loans another types of 2nd mortgage. It’s got a variable interest rate and a credit line you to definitely you might mark from the time you need it.
- Family collateral traces generally have a suck age of ten years with interest-only payments during this period. Adopting the mark period comes to an end, your repay one another dominant and interest.
- Lowest monthly installments derive from a changeable rate of interest. You can utilize the money again because you pay off the credit line.
- People get prefer a great HELOC once they greeting and then make occasional money to possess a home upgrade otherwise expenses.
- Certain residents and should provides a credit line available to have monetary emergencies. not, in the event the borrowing from the bank glides or you clean out your work, your financial you can expect to decrease your credit line or even close it.
How Are property Equity Mortgage and you may Next Financial Determined?
Lenders always only allow you to take-out a specific section of your property equity. Exactly how much you can purchase hinges on this new residence’s really worth and you will exactly how much you owe on the first mortgage.
To determine how much money you should buy, incorporate just how much we wish to borrow from what your debt in your first-mortgage. Split that contribution by your house’s latest appraised worthy of. Providing you with your the loan so you’re able to worth otherwise LTV.
Such, in the event your residence is worthy of $300,000 and you also are obligated to pay $200,000 on the first-mortgage, you have $100,000 from guarantee.