
Debt-to-earnings ratio

Debt-to-money ratio (DTI) means the newest percentage of your own gross monthly earnings designated toward month-to-month financial obligation payments (such as the upcoming homeloan payment).
For a conventional mortgage, loan providers like a beneficial DTI proportion significantly less than thirty six percent. Although not, DTIs around 43% can be enjoy. On occasion, you may even meet the requirements having good DTI as much as forty-five-50%, if you have compensating activities. These factors could include a premier credit rating or tall cash reserves held in the financial.
So you can calculate your own DTI proportion, seem sensible the monthly obligations repayments and you will separate one to share from the the month-to-month gross income. Like, for those who have a revenues from $5,000 and you may month-to-month financial obligation money from $step one,five-hundred, the debt-to-earnings ratio are 30 %.
Loan limitations
To locate a traditional compliant mortgage, your loan count have to slide contained in this local loan limits lay from the new Government Casing Fund Department (FHFA). These types of mortgage restrictions change a year, and are also high during the section that have very highest possessions opinions. Within the 2025, the newest conforming financing limitation for an individual-family home in the most common of your You.S. is actually $ , if you are higher-value mortgage limits rise to linked here help you $ . You can check the area’s current loan restrictions here.
In cases where loan amounts meet or exceed the restrict, individuals must make an application for a low-compliant loan otherwise an excellent jumbo financing. Jumbo finance typically wanted off payments starting anywhere between 10% and you can 20% down.
- Single-family home or multiple-unit household (only about five equipment)
- A residence, perhaps not a commercial possessions
- Structurally voice
- No claims contrary to the possessions
- Assessment requisite
- To own condos, no less than 51% away from complete gadgets need to be manager-filled or next home
In addition, loan providers enjoys protection in place to ensure that you dont obtain over your house may be worth. Once you’ve a finalized pick contract, your home loan company commonly arrange for a house appraisal to confirm that the sales rate will not exceed new property’s real market value.
Antique financing standards FAQ
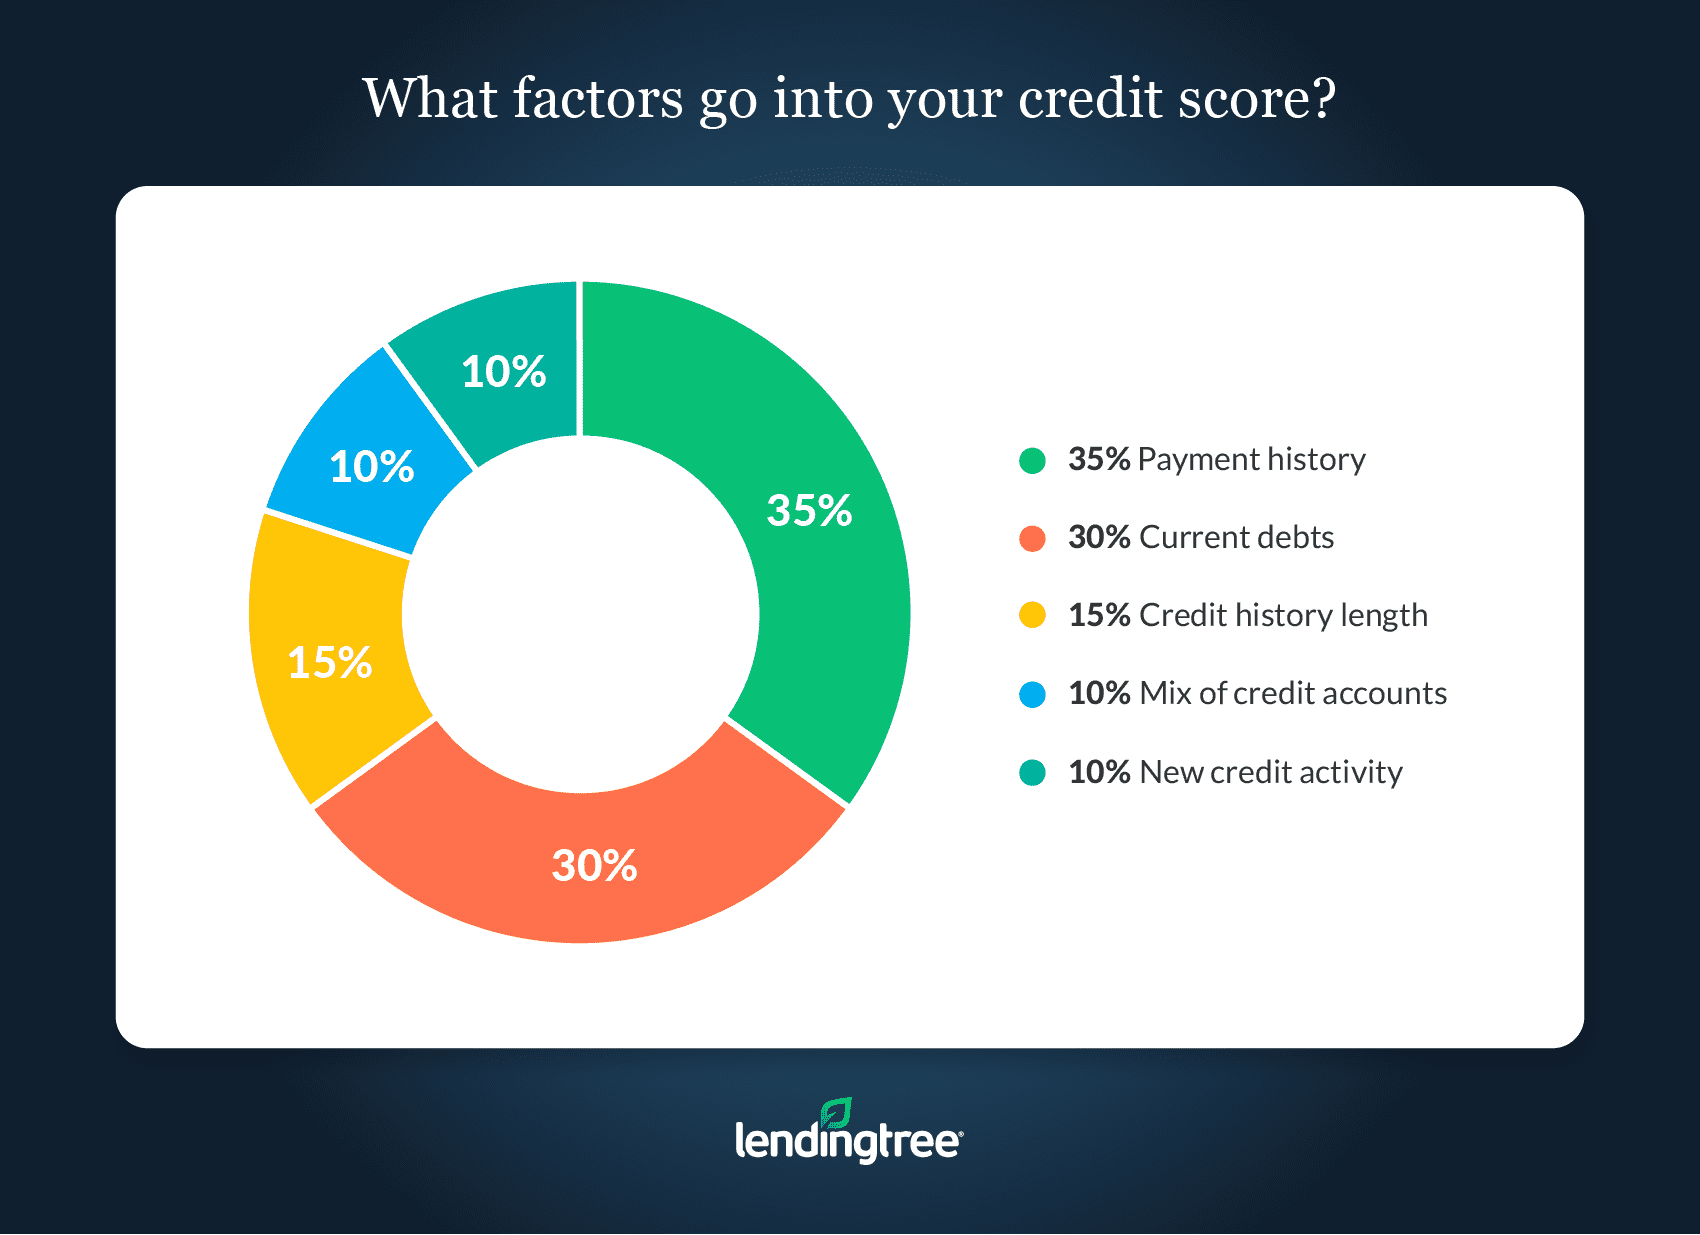
It is more straightforward to be eligible for a conventional loan than many very first-big date homebuyers anticipate. You will want a minimum credit rating out of 620 including a couple straight years of secure earnings and you will a job. Delivering recognized also demands the very least downpayment between 3 and you can 5 % and a loans-to-money ratio below 43 percent oftentimes.
In the present financial landscape, the idea that a 20 percent down payment is necessary was a myth. There are numerous home loan applications, along with old-fashioned finance, that provide much more versatile down payment possibilities. Particular earliest-go out homeowners can find in just step 3 per cent off, while some will need at the least 5 %. Just remember that , to order a home with less than 20 % down will require individual financial insurance rates.
Preferably, conventional lenders favor a max obligations-to-income proportion at the or less than thirty six per cent. This is basically the portion of the pre-tax month-to-month earnings one to goes to monthly debt money (home loan, auto loans, student education loans, minimal loans money, etc.). However, some loan providers enable it to be an optimum financial obligation-to-income ratio as high as forty five otherwise 50 percent in case the borrower have compensating points. Men and women can include a premier credit score, a more impressive down payment, or numerous months’ value of home loan repayments during the reserves just after closing.
A normal financing even offers far more positives than just a keen FHA mortgage in the event the you have a good credit score (as much as 680 or more) at least 3 % down. not, in case the credit rating is in the high-500s otherwise reduced-600s, an FHA financing could be a cheaper solution. That’s because FHA loans try not to charge higher financial insurance fees to own individuals that have down credit. But not, keep in mind that old-fashioned personal financial insurance policies are canceled once you’ve adequate home guarantee whereas FHA home loan insurance policy is always permanent.